
With the price of gold and silver continuing to see significant volatility, one of the greats in the business released this.

Gold Down, Silver Down—Calm Down
November 19 (King World News) – Matthew Piepenburg, partner at VON GREYERZ: Having just come off nine days of gold presentations in two languages, three cities and even more price swings, it’s time for a reality check on the price action in gold and silver, both of which have reached bear territory this year, with silver falling twice as fast.
Are we worried?
No. We are buying.
Time Not Timing
For those speculators agnostically trading the metals long or short in a market-timing maze of buy/sell signals, nothing explained below will resonate.
This is because we are buyers rather than traders of precious metals.
We see gold and silver as monetary metals confronting a monetary sea change in which the compounding impact of inflation will reduce fiat currency purchasing power by at least 70% in the next decade.
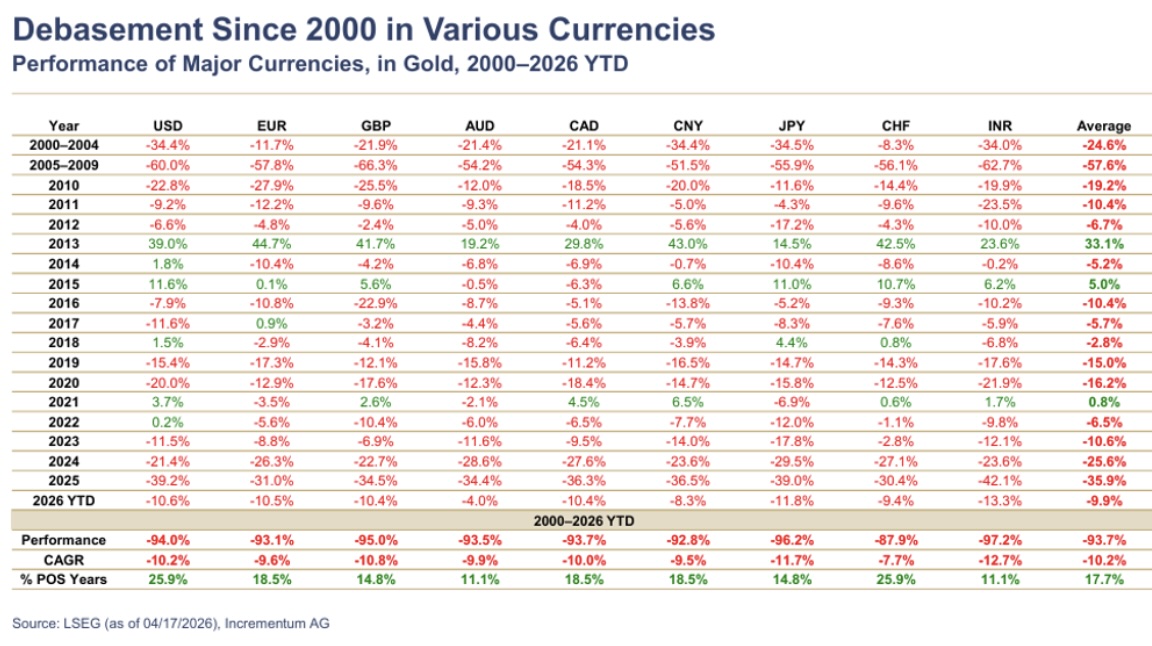
In this hard light of wealth preservation, our focus is time, not timing. And our store of value, confirmed by centuries, is real money not paper currencies.
And time, as the song says, is on our side.
Many, of course, will see this as apologetics from sell-side “gold bugs.”
But for those who understand history, math and risk management, the case for precious metals is as obvious today as a cavity to a dentist.
Gold’s longer-term trajectory is now mathematically assured by its inverse relationship to paper currencies. In this light, the price falls of 2026 are effectively a buyer’s gift.
Peak Lunacy, Not Peak Gold
We are very far from peak gold, but simultaneously at the apex of what the American bond king, Jeffrey Gundlach, described as “peak lunacy.”
In fact (and coming as no surprise to any familiar with my obsession with credit markets), if one seeks conviction in gold, the signals begin in those boring and hence ignored credit markets.
And yes, the objective lunacy of the global credit profile is staggering…
Listen to the greatest Egon von Greyerz audio interview ever
by CLICKING HERE OR ON THE IMAGE BELOW.

Private Credit’s Pain Delay
As warned earlier this year, the “weapons of mass destruction” lurking within the private credit minefield have only grown more threatening.
These private credit books are held by a wide range of insurance, annuity and pension funds holding the very same folio of loans yet at extremely diverse valuations.
From a perfect par score of 100, for example, the same book of loans marked by entity “X” at 90, will be marked by entity “Y” at 20 or 30. Based on real math, the entire private credit space deserves little more than a triple-C rating (with scores at 60), and that’s being very generous.
This valuation disparity is partly due to the fact that ratings agencies with staffs of thirty can not effectively underwrite thousands of credits.
But the darker truth is that these PC funds are just lying about their homemade valuations and hoping for a miracle to save them. This explains why investors in their gated funds can only get 5% of their money out per quarter.
Their pain cannot be avoided, merely postponed.
Even More Lunacy: From Private Equity to AI
Then there is private equity, another credit bug looking for a windshield.
Its prior LBO (levered buy-out) model succeeded on a premise of cheap credit with rates at 0% to 2%. Those days and rates are over, yet an entire generation of PE sponsors, who have never seen rates above 5%, still pretend to be what they once were.
Far worse, of course, is the greatest misallocation of capital and credit in the history of capital markets, namely the AI Nirvana-to-Nightmare template.
Not only have five tech hyper-scalers (who account for 90% of the S&P’s earnings) grossly over-invested $1.1 trillion in AI CAPEX, they’ve also squandered an additional $3T in off-balance-sheet debt in two AI monopolies (OpenAI and Anthropic) showing respective operating losses of $8B and $14B.
The quarter-over-quarter margins for these two un-moated tech fantasies are falling, not rising. In short, AI’s best days have passed, yet the market prices its future for perfection.
No one believes the ratings on these credits, the spreads of which are widening. Soon, this credit boom will mathematically morph into yet another credit bust as investors revolt, credit tanks and defaults peak in a reckoning reminiscent of 2008.
Meanwhile, as everyone from CoreWeave to Google is burning through cash and competing for your data center sucker-money, the markets are turning a blind eye to default risk whose objective levels surpass the sub-prime crisis (and mis-ratings) of the GFC.
Ultimate Lunacy—Sovereign Debt
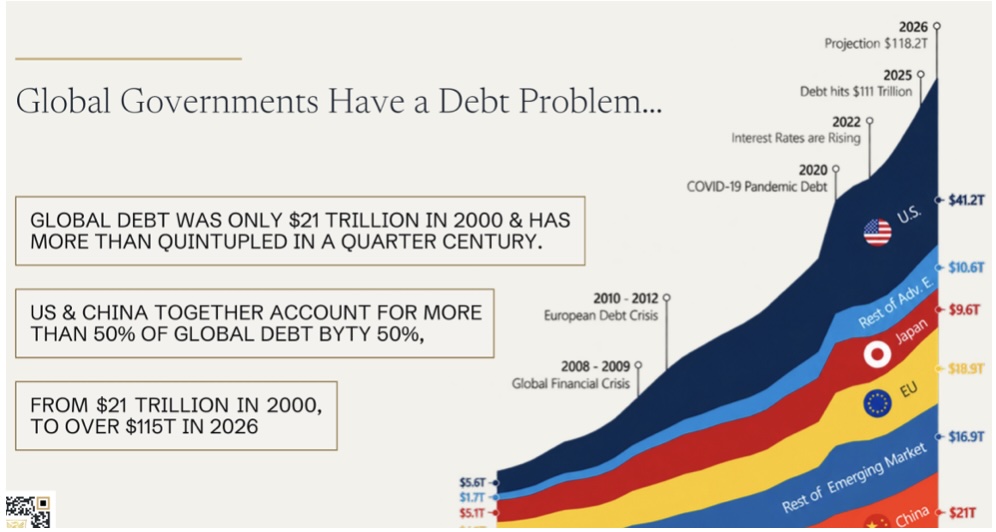
But if such lunacy in private credits wasn’t scary enough, just look at government debt. In the last 25 years, global government debt has skyrocketed by >5X from $21T to $115T.
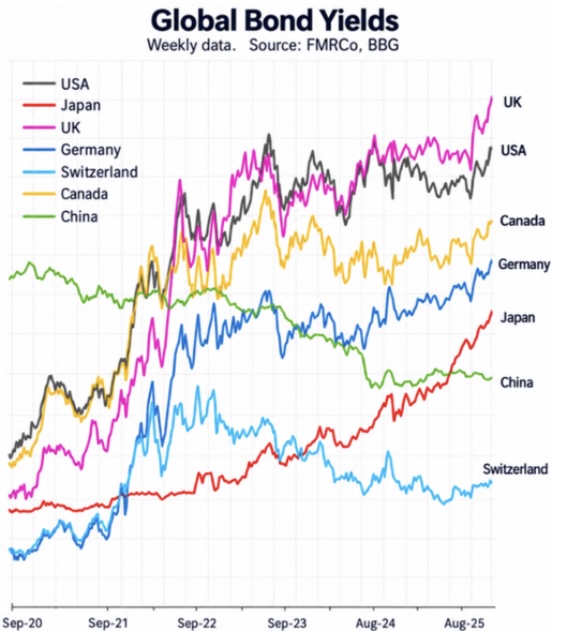
What’s worse, is that the cost of that debt has reached decade highs, as evidenced by the decade highs in sovereign bond yields.
And as for the home of the world reserve currency, it spends over $7.5T per year against an income of just $5T.
Just six years ago, U.S. public debt was $23T and the cost of borrowing was 0.5%.
Today, that debt is over $40T, and the cost of borrowing is above 5%.
Do the math…
Very soon, Uncle Sam’s only options will be constructive default or bazooka money, either of which will send precious metals well beyond their prior highs of January, 2026.
Chasing Yield, Ignoring Disaster
Despite these warnings, patterns and patient signals, today’s desperate debt issuers and equally desperate yield-chasers are thinking only of timing their next trade rather than contemplating these historical risks.
They see $1.9T of 2026 investment grade bond issuance with coupons as high as 6% to 8%; they see USTs offering 5% to 6% yield. And they tell themselves this “sure beats a yield-less pet rock.”
Such optimized herd-thinking is nothing new. As the institutional “smart money” goes further out on the risk branch looking for yield and laughing at gold to make their annual performance bonus, what they are refusing to see would be almost comical, if it was not otherwise so tragic.
In particular, this lunatic market has three key blind spots.
Blindspot 1: Measuring Yield in a Melting Currency.
It can feel nice to see nominal bond yields rising; but what investors overlook is that when measuring their yields in gold rather than dollars, they are in fact losing not winning.
Even that sacred 10Y UST, which the world perceives as “risk-free-return,” has lost 90% over the last 12 years when measured in gold rather than dollars.
But this is what happens to a currency whenever its M2 money supply (driven by credit expansion at the banks) increases by 45% in just six years. Its purchasing power melts unnoticed until, like Hemingway’s description of poverty, it goes from slowly to all at once.
Blindspot 2: “Positive Yield” Is an Open Lie.
Those observing this year’s dramatic price falls in gold point to the traditional argument that investors see an opportunity cost in holding a yield-less pet rock vs. a higher yielding bond market.
But this logic assumes the bond market (from SpaceX and Google Bonds [all trading well below par] to Uncle Sam’s IOUs) are actually beating inflation.
And for those who believe that the current CPI inflation scale from the BLS represents honest inflation reporting, then yes, bonds offer more positive yield than precious metals.
But anyone who can fog a mirror and count to ten knows better.
Not only do we all FEEL inflation at a much higher rate than the official 3.7%, the more honest measures of inflation literally confirm inflation at closer to 10%.
How do I know this?
Well, if we use the same scale Volcker used in the 1980’s (before the BLS began over 20 revisions of its BS CPI scale to hide inflation), we would be staring down the barrel of at least 11% inflation right now.
Alternatively, if like Michael Green, we simply measured the annual inflation rate by the annual rate of debt increase, or if, like Jeffrey Gundlach, we measured the annual inflation rate by our import and export rates, we’d derive a similar and more honest inflation rate of at least 9%.
In other words, using real math rather than BLS lies, we’d realize that not a single UST across the entire yield curve is actually beating inflation or offering positive yield.
This is not fable but fact. This is honest math.
More importantly, this is just history repeating itself.
Blindspot 3: Governments Are Playing Rather than Serving You.
As I’ve written countless times, and as others from Russell Napier to Richard Werner have confirmed, broke nations don’t want to see inflation go away, they want more of it.
The oldest trick in the book for debt-soaked (and hence failing nations) is to destroy their debt by destroying their currency, i.e. “inflating away their debt.”
The fancy lads call this “financial repression” or “negative real rates,” and what it all boils down to is making sure the inflation rates are higher than the costs of their debt (or bond yields).
But here’s the rub: The kind of inflation rates needed to surpass the yields on the 10Y UST (currently yielding 5.13%) are extremely embarrassing and hence politically toxic to the political and economic opportunists who have mismanaged our national balance sheet for decades.
Their solution?
Easy.
Just lie about the inflation rate. This trick is great for Uncle Sam, but highway robbery to his citizens.
And that, by the way, is the very nature of Warsh’s “inflation task force” or new “trimmed median PCE inflation” scale. It’s simply another lie from on high.
Stated even more simply: Your “risk-free-return” is literally return-free-risk.
Getting Back to Gold & Silver.
But what do all these bond signals and political tricks have to do with the inevitable blast-off in gold? How can we be so certain of precious metal prices surpassing prior highs and confirm that we are nowhere near “peak gold”?
In other words, how can we, or anyone, track the patterns of tomorrow?
It’s actually simple, because the patterns of yesterday are repeating themselves with almost eerie clarity.
Toward this end, the astounding brevity of investor memory is a bit scary.
Rising Yields + Rising Debt = More Debasement & Rising Gold
It was only a few years back when we saw an almost identical debt-and-rate setup for dramatically rising gold.
Remember 2022-2024 and Powell’s “higher for longer” policies of rising rates and Fed balance sheet tightening to allegedly “fight inflation,” which he had previously said was only “transitory”?
As I warned then, Powell’s America and then $33T debt levels could never afford a rising yield/rate environment without breaking the system and inevitably being forced to resort to bazooka money, screaming dollar debasement and a rising gold price.
Unlike Volcker, who could raise rates to fight inflation when U.S. debt was less than 1T, Powell (and now Warsh) have no such options when debt levels are in the $40T arena.
The hard math of fiscal dominance empirically tells us that Uncle Sam can’t afford to be a hawk for any extended period. Too many things break in a high rate (cost of debt) environment, forcing an inevitable pivot to more fantasy money and an inflationary endgame.
And as for breaking things, remember that 2022-2024 period of climbing rates? 2022 saw the worst nominal returns in stocks and bonds since 1871. And as for 2023, the crashing bond market which Powell’s rising rates created, also induced the greatest banking crisis since 2008.
And what happened next? After 2 years of rising yields and 500 basis points of rate hiking, Powell caved, the money printing and rate cutting kicked in, and 2025 saw gold and silver ripping moon-bound.
Folks, that was just a year ago—and yet already, no one sees the familiar set up for what’s inevitable in the months and years ahead as pundits scream “peak gold” and AI leads the retail plankton (emergency liquidity) into yet another equity and credit disaster marked by rates and yields the USA simply can’t afford.
In short, very soon, the Fed and U.S. Treasury, after exhausting all their desperate options and narratives (from stablecoin miracle solutions to AI growth miracles), will have to once again face the hard math of not enough natural demand for their over-indebted and weaponized IOUs, and not enough GDP or tax receipts to service their debts.
Drumroll the Mouse-Clicker
Other than the political sin of default, the only option left for our trapped elites in DC will be trillions in more mouse-clicked liquidity, a likely gold-revaluation and hence another patterned, “debasement trade” tailwind for precious metals, with silver racing the fastest in the next uptrend.
This pattern has nothing to do with timing.
It has everything to do with time.
And for those who understand history’s patterns and math’s cruel honesty, we gold INVESTORS (unconstrained by margin calls, stop-loss deadlines and annualized return bonuses) have all the time we need to watch this next cycle play itself out. For those who would like to read more fantastic articles from Matthew Piepenburg, Egon von Greyerz, Alasdair Macleod and Ronnie Stoeferle CLICK HERE.
ALSO RELEASED!
This Is All You Need To Read After Today’s Brutal Takedown CLICK HERE.
The Stock Market Meltdown Has Officially Started CLICK HERE.
STOCK MARKET COLLAPSE WARNING: Here’s What To Expect From Gold & Silver CLICK HERE.
Trump Trade Will Send The Price Of Gold To $6,500 CLICK HERE.
MICHAEL OLIVER: Most Important Special Report MSA Has Ever Released! CLICK HERE.
$10,000 Gold, $500 Silver And The Tech Bubble CLICK HERE.
© 2026 by King World News®. All Rights Reserved. This material may not be published, broadcast, rewritten, or redistributed. However, linking directly to the articles is permitted and encouraged.